Central Banks and Forex: Fed, ECB, BoE and BoJ Explained
Central banks and forex explained: what the Fed, ECB, BoE and BoJ aim for, the tools they use, when they speak and how their decisions move currencies.

Almost every big trend in a major currency pair leads back to a few committees of economists sitting around a table in Washington, Frankfurt, London and Tokyo. Trading forex means knowing who they are, what they want and when they speak.
Quick answer: Central banks drive forex because they set interest rates, the biggest reason money flows into or out of a currency. The four that matter most are the Fed (USD), ECB (EUR), Bank of England (GBP) and Bank of Japan (JPY). Each meets eight times a year, and the market moves on how their decisions and words compare with expectations.
Central banks and forex: why every pair has two central banks
A central bank is the public institution that manages a country’s money. It sets the short-term interest rate that commercial banks pay to borrow overnight, it acts as lender of last resort when banks get into trouble, and in most countries it holds the nation’s foreign currency reserves. The major central banks are independent of day-to-day politics, but their goals are set by law.
The policy rate is the price of holding a currency. When a central bank raises it, deposits and bonds in that currency pay more, and global investors have a reason to buy it. When it cuts, the reason weakens. Our guide on how interest rates affect currency prices walks through that chain link by link, so this article focuses on the institutions themselves.
Because forex is always quoted in pairs, every pair sits between two central banks. EUR/USD is a contest between the European Central Bank and the Federal Reserve. GBP/USD sets the Bank of England against the Fed. USD/JPY pits the Fed against the Bank of Japan. A pair rarely moves for long because of one bank alone; it moves when the two banks are expected to head in different directions, or at different speeds.
That is why experienced traders talk about policy divergence. If the Fed is expected to keep rates high while the ECB is expected to cut, the gap favours the dollar, and EUR/USD tends to drift lower over weeks or months. If both are cutting at the same pace, the gap barely changes and other forces, such as growth data or the market’s mood, take over. The Academy lesson on what moves currencies places rates alongside those other drivers.
Central bank mandates: what each bank is trying to achieve
Every central bank works to a mandate, the goal it has been given by law, and every decision is justified in its terms.
The common thread is inflation. All four major central banks aim for inflation of 2% a year over the medium term. They differ in how they measure it, how strictly they treat the target, and what else they are asked to care about.
- The Federal Reserve has a dual mandate: maximum employment and stable prices. It defines stable prices as 2% inflation measured by the PCE price index, a broader gauge than the better-known CPI. Because jobs are written into its mandate, US employment data moves the dollar more than it might otherwise, which is part of why non-farm payrolls is such a big event.
- The European Central Bank has a single primary mandate: price stability across the euro area. Its target is 2% over the medium term, and it describes the target as symmetric, meaning it treats inflation below 2% as just as undesirable as inflation above it.
- The Bank of England targets 2% CPI inflation, a target set by the UK government rather than chosen by the bank. If inflation misses by more than one percentage point in either direction, the Governor must write an open letter to the Chancellor explaining why and what the bank will do about it.
- The Bank of Japan adopted a 2% price stability target in 2013, after many years in which Japan’s problem was prices that fell rather than rose.
The smaller central banks set their goals slightly differently, often as a range. The chart below lines up all eight.
The mandate tells you how a bank will react to new data. When inflation runs above target, a central bank leans towards higher rates, or keeps them high for longer. When inflation is falling and unemployment rising, it leans towards cuts. That is why CPI releases move currencies: they change what the central bank is likely to do next. The Academy lesson on inflation and CPI shows how to read one.
Central banks also move through a recognisable cycle, raising rates as an economy heats up and cutting as it cools. Tap each phase below to see what the bank, and the currency, tend to do.
Hiring is strong, spending rises and inflation starts to pick up. The central bank begins raising rates to keep it in check.
Currency: Usually strengthens: rising rates attract capital and growth attracts investment.
The economic cycle from a central bank's point of view: rates rise through expansion, peak with inflation, and fall in a slowdown. The currency tends to follow the expected path of rates, usually a little ahead of it.
The central bank toolkit: rates, guidance, QE and intervention
Central banks have four main tools that matter for currencies. They are not used equally often, and they do not have equal force.
The policy rate
This is the main lever, reviewed at every scheduled meeting. Each bank names it differently: the federal funds rate (set as a target range) at the Fed, Bank Rate at the Bank of England, the deposit facility rate at the ECB (it sets three rates, but this is the one markets watch) and the short-term policy rate at the Bank of Japan. Changes are usually made in steps of a quarter of a percentage point, and larger steps are a sign of urgency.
Forward guidance
Forward guidance is what a central bank says about its future decisions. It might be a sentence in the statement, a projection of where rates are heading, or a speech by the Governor. Because markets trade the future, guidance often moves currencies more than the rate decision itself. The most famous example came in 2012, when the then ECB President Mario Draghi said the bank would do “whatever it takes” to preserve the euro. The words alone calmed a crisis.
Guidance is where the language of hawkish and dovish comes from: hawkish means leaning towards higher rates, dovish towards lower ones. Our article on hawkish vs dovish covers how to read that language phrase by phrase.
Quantitative easing and tightening
When rates are already near zero and the economy still needs help, a central bank can buy government bonds with newly created money. This is quantitative easing (QE). The Bank of Japan pioneered it in 2001; the Fed and the Bank of England followed after the 2008 financial crisis, and the ECB launched large-scale purchases in 2015. The reverse, letting bonds mature without replacing them or selling them, is quantitative tightening (QT).
Currency intervention
Occasionally a central bank, or the finance ministry that instructs it, buys or sells currency directly to change the exchange rate. In Japan, for example, the Ministry of Finance decides and the Bank of Japan carries out the trades, as our USD/JPY trading guide explains. Intervention is rare, expensive and often only temporary if it fights the interest rate gap.
The most dramatic lesson in its limits came from Switzerland. In September 2011 the Swiss National Bank set a minimum exchange rate of 1.20 francs per euro and promised to buy foreign currency in unlimited amounts to defend it. On 15 January 2015 it abandoned the floor without warning, and EUR/CHF collapsed through parity within minutes. Step through a sketch of it below.
Illustrative daily EUR/CHF candles around the Swiss National Bank's January 2015 decision to drop its 1.20 floor. Shapes are simplified and are not exact historical prices.
The big four compared: Fed, ECB, BoE and BoJ
These four banks issue the currencies on the busiest side of the market. The US dollar alone is on one side of close to nine in ten forex trades, according to the Bank for International Settlements, which makes the Fed the single most influential institution for anyone trading currencies.
| Central bank | Currency | Who decides | Meetings a year | Inflation goal | What else to watch |
|---|---|---|---|---|---|
| Federal Reserve (Fed) | USD | Federal Open Market Committee (FOMC), 12 voters | 8 | 2% (PCE) plus maximum employment | Dot plot of rate projections, four times a year |
| European Central Bank (ECB) | EUR | Governing Council | 8, about every six weeks | 2%, symmetric | Staff projections, four times a year |
| Bank of England (BoE) | GBP | Monetary Policy Committee (MPC), 9 members | 8 | 2% CPI, set by the government | The vote split; quarterly Monetary Policy Report |
| Bank of Japan (BoJ) | JPY | Policy Board, 9 members | 8, two days each | 2% | Quarterly Outlook Report; currency comments from the Ministry of Finance |
The Federal Reserve
The Fed’s decisions are made by the FOMC. Not every member votes every year, which matters when you hear a Fed official speak: a voter’s views carry more weight for the next decision than a non-voter’s.
The decision is released at 2pm New York time, usually 7pm in the UK, and the Chair holds a press conference half an hour later. Four times a year the Fed also publishes the Summary of Economic Projections, including the dot plot: each member’s anonymous estimate of where rates should be at the end of the next few years. A shift in the dots can move the dollar more than the decision.
The European Central Bank
The ECB sets one interest rate for every country that uses the euro, so its Governing Council combines the six members of its Executive Board with the governors of each euro area national central bank. It announces at 2:15pm Frankfurt time, with a press conference at 2:45pm. Because it serves economies as different as Germany and Greece, it tends to move cautiously, and it pays close attention to the gap in borrowing costs between member states. Our EUR/USD trading guide shows how the ECB and the Fed share control of the world’s most traded pair.
The Bank of England
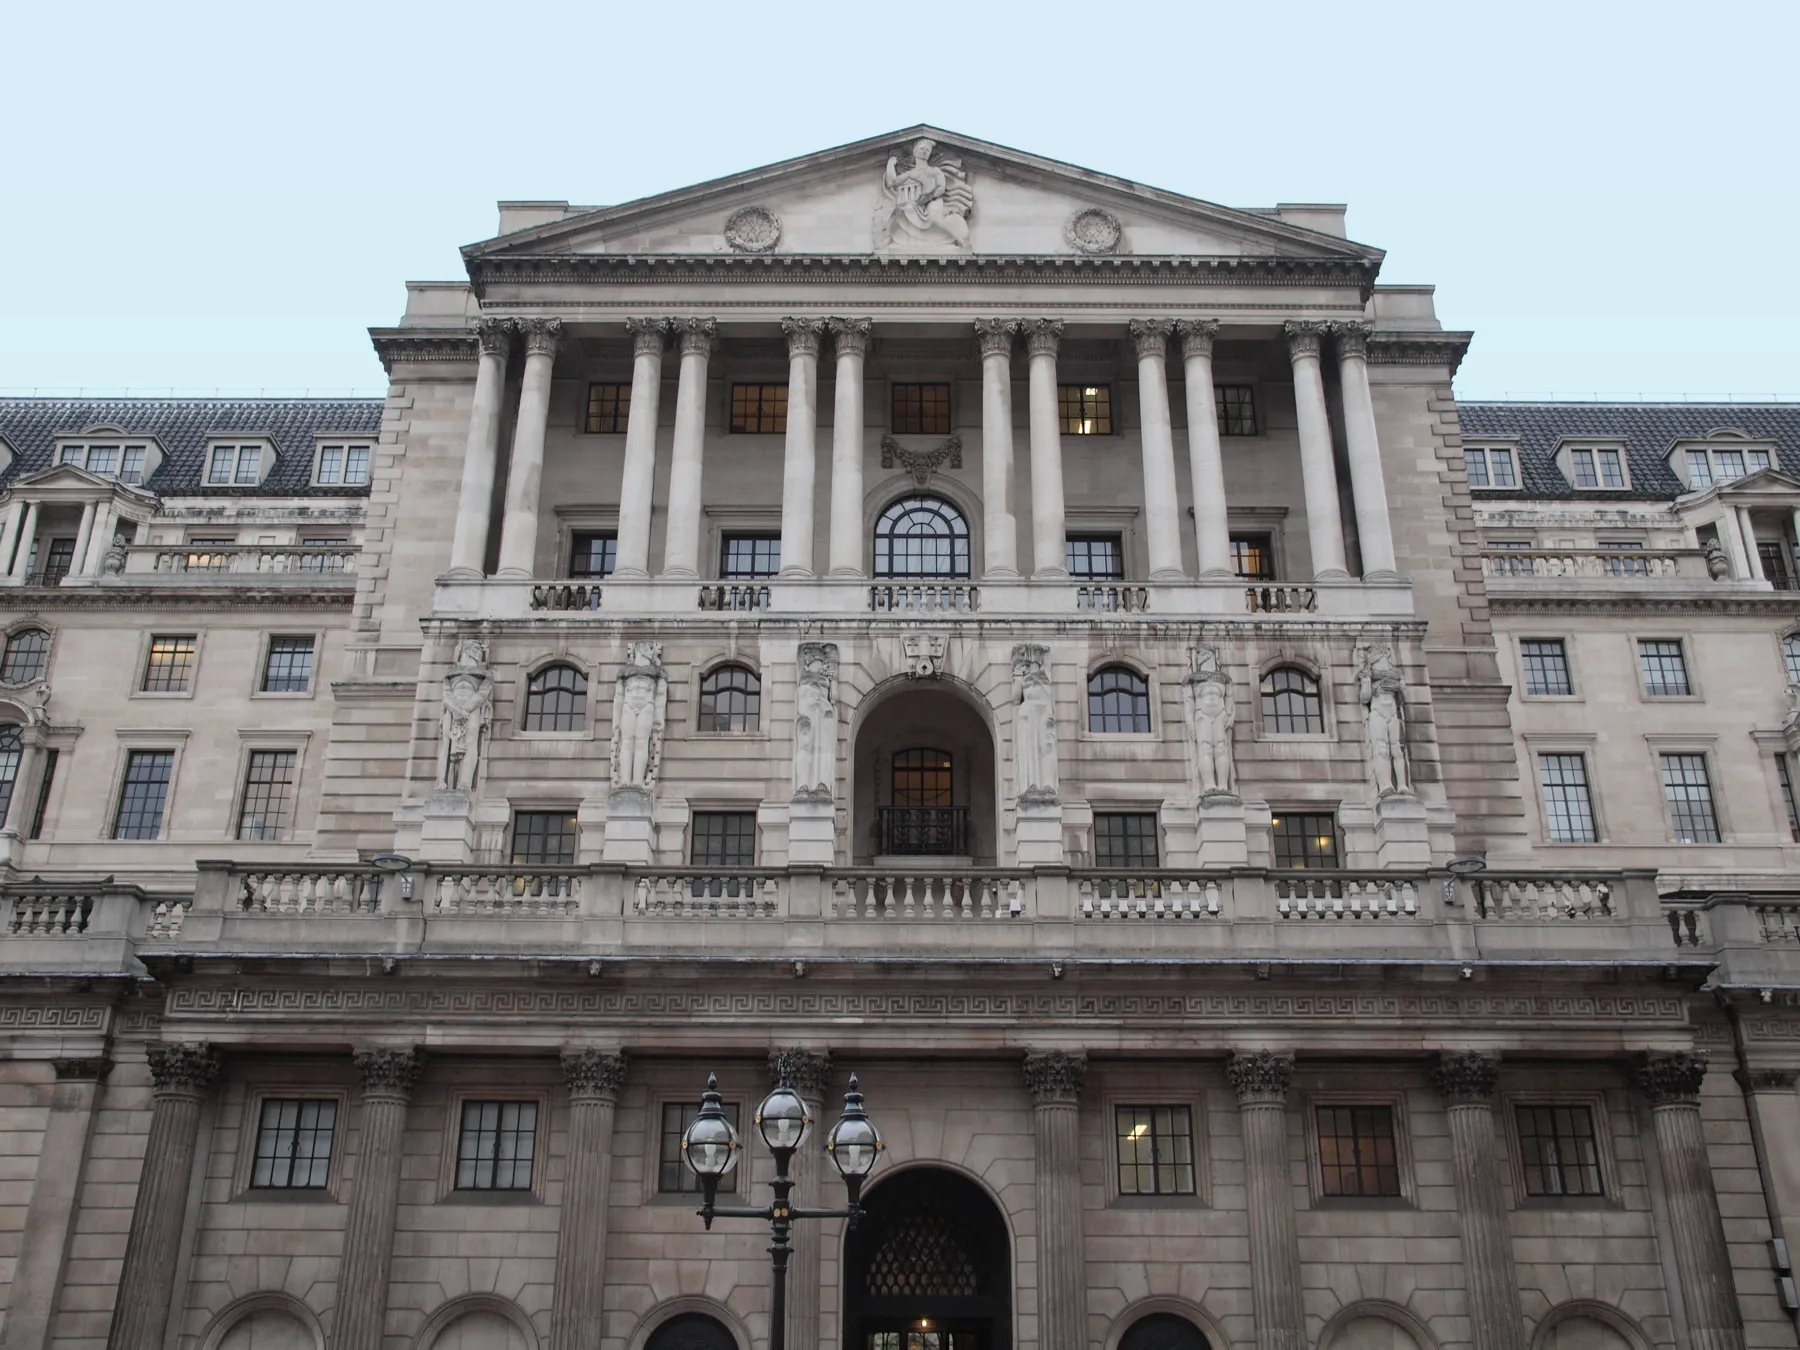
The MPC has nine members: the Governor, three Deputy Governors, the Chief Economist and four external members appointed from outside the bank. Each member’s vote is published at noon London time alongside the decision and the minutes, and that is what makes the BoE unusual. A decision to hold rates can still be a surprise if the vote is closer than expected. Try reading one below.
How would you read this?
Markets expect the Bank of England to hold Bank Rate with a 7–2 vote, the two dissenters voting for a cut. At noon the bank holds, as expected, but the vote is 5–4: four members voted to cut. GBP/USD drops 40 pips within a minute. What has happened?
The Bank of Japan
The BoJ spent most of the period from the late 1990s with rates at or near zero, and pioneered QE, negative rates and a policy of capping long-term bond yields. That long era of ultra-low rates is why the yen became the classic funding currency for the carry trade, explained further in our guide to the carry trade. Its meetings last two days, and the decision comes with no fixed release time, usually around midday in Tokyo, which is the early hours in London.
The smaller central banks: SNB, RBA, BoC and RBNZ
Four more central banks matter for the other major pairs. They are smaller, but their currencies react strongly to their decisions, and each carries an extra driver you need to know.
The Swiss National Bank meets only once a quarter, so each decision carries more weight. Because the franc is a safe haven that tends to rise when markets are frightened, the SNB’s problem has usually been a currency that is too strong, and it has been one of the most willing major central banks to intervene. Our USD/CHF trading guide and the article on safe-haven currencies cover the franc in depth.
The Reserve Bank of Australia cut its meetings from eleven to eight a year from 2024. Its currency also follows Chinese demand and commodity prices, so an RBA decision is only part of what moves AUD/USD; see our AUD/USD trading guide.
The Bank of Canada announces on eight fixed dates a year. With so much of Canada’s trade going to the United States, its decisions are often read alongside the Fed’s, and oil prices sit in the background of every move; our USD/CAD trading guide explains the link.
The Reserve Bank of New Zealand was the first central bank in the world to adopt a formal inflation target, in 1990, and it publishes its own projected path for its official cash rate. That makes its forward guidance unusually explicit: a change in the projected path is often the real news.
The central bank communication calendar
Central banks rarely surprise markets on purpose. Between decisions they release a steady stream of information, and each piece shifts what the market expects from the next meeting. Knowing that rhythm tells you when a currency is likely to be quiet and when it is likely to move.
Here is how the pieces fit together for the big four.
- Decision and statement. Released at a fixed time: 2pm New York (Fed), 2:15pm Frankfurt (ECB), noon London (BoE), and around midday Tokyo with no fixed minute (BoJ). Compare the wording with the previous statement; a single dropped or added phrase can be the real news.
- Press conference. The Fed and ECB hold one after every decision, the BoJ Governor speaks in the Tokyo afternoon, and the BoE holds one alongside its quarterly Monetary Policy Report. Answers to unscripted questions often move a currency more than the prepared statement.
- Minutes or accounts. The BoE publishes its minutes with the decision. The Fed releases minutes three weeks after each meeting, the ECB publishes an account about four weeks later, and the BoJ issues a Summary of Opinions about a week later. These show how divided the committee was.
- Speeches and data. Between meetings, officials give speeches and testimony, and each new inflation or jobs release changes the odds of the next move. This is where most of the expectation-building happens.
- Quiet period. In the days before a decision, officials stop commenting on policy. At the Fed this blackout begins on the second Saturday before the meeting. Markets often drift sideways as they wait.
All of these dates appear on an economic calendar, usually marked as high impact, and the central banks publish their own meeting schedules well in advance (the Fed’s FOMC calendar is a good example). Our step-by-step guide on how to read an economic calendar and the Academy lesson on the economic calendar show how to set one up for the currencies you trade.
How to use central bank analysis in your own trading
None of this tells you which way to trade. It gives you context on why a pair is trending, which days are likely to be volatile, and how much of your account is really exposed to a single event. Three habits turn that context into better decisions.
First, know the stance of both banks in every pair you trade. Write one line for each: hiking, holding or cutting, and whether the next move is expected to be sooner or later. If both lines point the same way, the pair is unlikely to trend on rates alone.
Second, mark every central bank event for your currencies a week ahead. Decisions, press conferences, minutes and big speeches. Then decide in advance what you will do with open positions, because spreads widen and prices can jump through stop orders at the moment of release, causing slippage. Our guide to slippage in forex explains why.
Third, count your exposure to each central bank, not just each pair. Several positions that look different can all depend on the same decision, as the example below shows.
The same arithmetic applies to any bank. A long AUD/USD position and a long NZD/USD position are two bets against the dollar and two bets on risk appetite at once. Our guide to currency correlation and the Academy lesson on correlation risk show how to spot these overlaps before they hurt.
Common mistakes traders make with central banks
Watching the decision and ignoring everything around it
Most rate decisions are priced in long before they are announced. The news is usually in the vote, the statement wording, the projections or the press conference. If you only read the headline number, you will often be confused by the reaction.
Watching only one side of the pair
A hawkish Fed need not mean a falling EUR/USD if the ECB is turning hawkish faster. Every pair has two central banks, and the pair follows the gap between them.
Treating a central bank promise as permanent
Forward guidance is conditional, and floors, caps and targets can be dropped. The Swiss franc in 2015 is the clearest reminder that a level defended by policy can vanish in minutes. Size positions so that a surprise from a central bank is a bad day, not a lost account.
Confusing intervention with a trend change
Direct intervention can move a pair hundreds of pips in minutes, but if the interest rate gap behind the trend has not changed, the effect can fade. Do not assume the first intervention ends the trend, and do not assume it will not happen again.
Forgetting the calendar between meetings
Minutes, testimony and speeches can move a currency sharply, yet many traders only mark the decision itself.
Frequently asked questions
Which central bank has the most influence on forex?
The Federal Reserve. The US dollar is on one side of close to nine in ten forex trades, according to the Bank for International Settlements, so Fed decisions affect almost every major pair at once. The ECB is next in importance, because EUR/USD is the most traded pair in the world.
How often do central banks meet to set interest rates?
The Fed, ECB, Bank of England and Bank of Japan each hold eight scheduled policy meetings a year, roughly every six weeks. The Reserve Bank of Australia and Bank of Canada also decide eight times a year, the Reserve Bank of New Zealand seven times, and the Swiss National Bank four times. All publish their dates in advance.
What time are central bank rate decisions announced?
The Fed announces at 2pm New York time, usually 7pm in the UK. The ECB announces at 2:15pm Frankfurt time, and the Bank of England at noon London time. The Bank of Japan has no fixed time, but usually announces around midday in Tokyo, which is the early hours of the morning in the UK.
How does quantitative easing affect a currency?
Quantitative easing means a central bank buys bonds with newly created money. That pushes bond yields down, which makes the currency less attractive to hold, so it tends to weaken. Quantitative tightening, shrinking those bond holdings, tends to do the reverse. The effect works gradually and depends on what markets already expected.
Can a central bank control its exchange rate?
Only partly, and usually only for a while. A central bank can buy or sell its own currency, and it can steer it through interest rates, but it cannot hold a level for ever against the market. The Swiss National Bank's decision to drop its EUR/CHF floor in 2015 shows how quickly a defended level can disappear.
Free course
Learn this step by step
“Fundamental Analysis” is a free BrokerCut Academy course: 9 short lessons (about 70 minutes), quizzes, interactive tools and a certificate when you finish.
Enrol free