Commodity Currencies: How Oil and Metals Drive CAD and AUD
Commodity currencies explained: why CAD follows oil, AUD follows iron ore, NZD and NOK follow their exports, and why the links break when you lean on them.

Oil jumps overnight and the Canadian dollar is already stronger before a single Canadian figure is published. Iron ore slides for a week and the Australian dollar drifts lower with it. If you trade CAD or AUD pairs, commodity currencies explain moves that otherwise look random.
Quick answer: Commodity currencies belong to countries that earn a large share of their income from exporting raw materials. The Canadian dollar tends to follow oil, the Australian dollar iron ore and coal, the New Zealand dollar dairy, and the Norwegian krone oil and gas. The links are real but loose: interest rates and risk mood often override them.
What are commodity currencies?
A commodity currency is the currency of a country whose exports are dominated by raw materials: energy, metals or farm goods. When the price of those goods rises, the country earns more from the rest of the world, its economy tends to do better, and its currency tends to strengthen. When prices fall, the reverse happens.
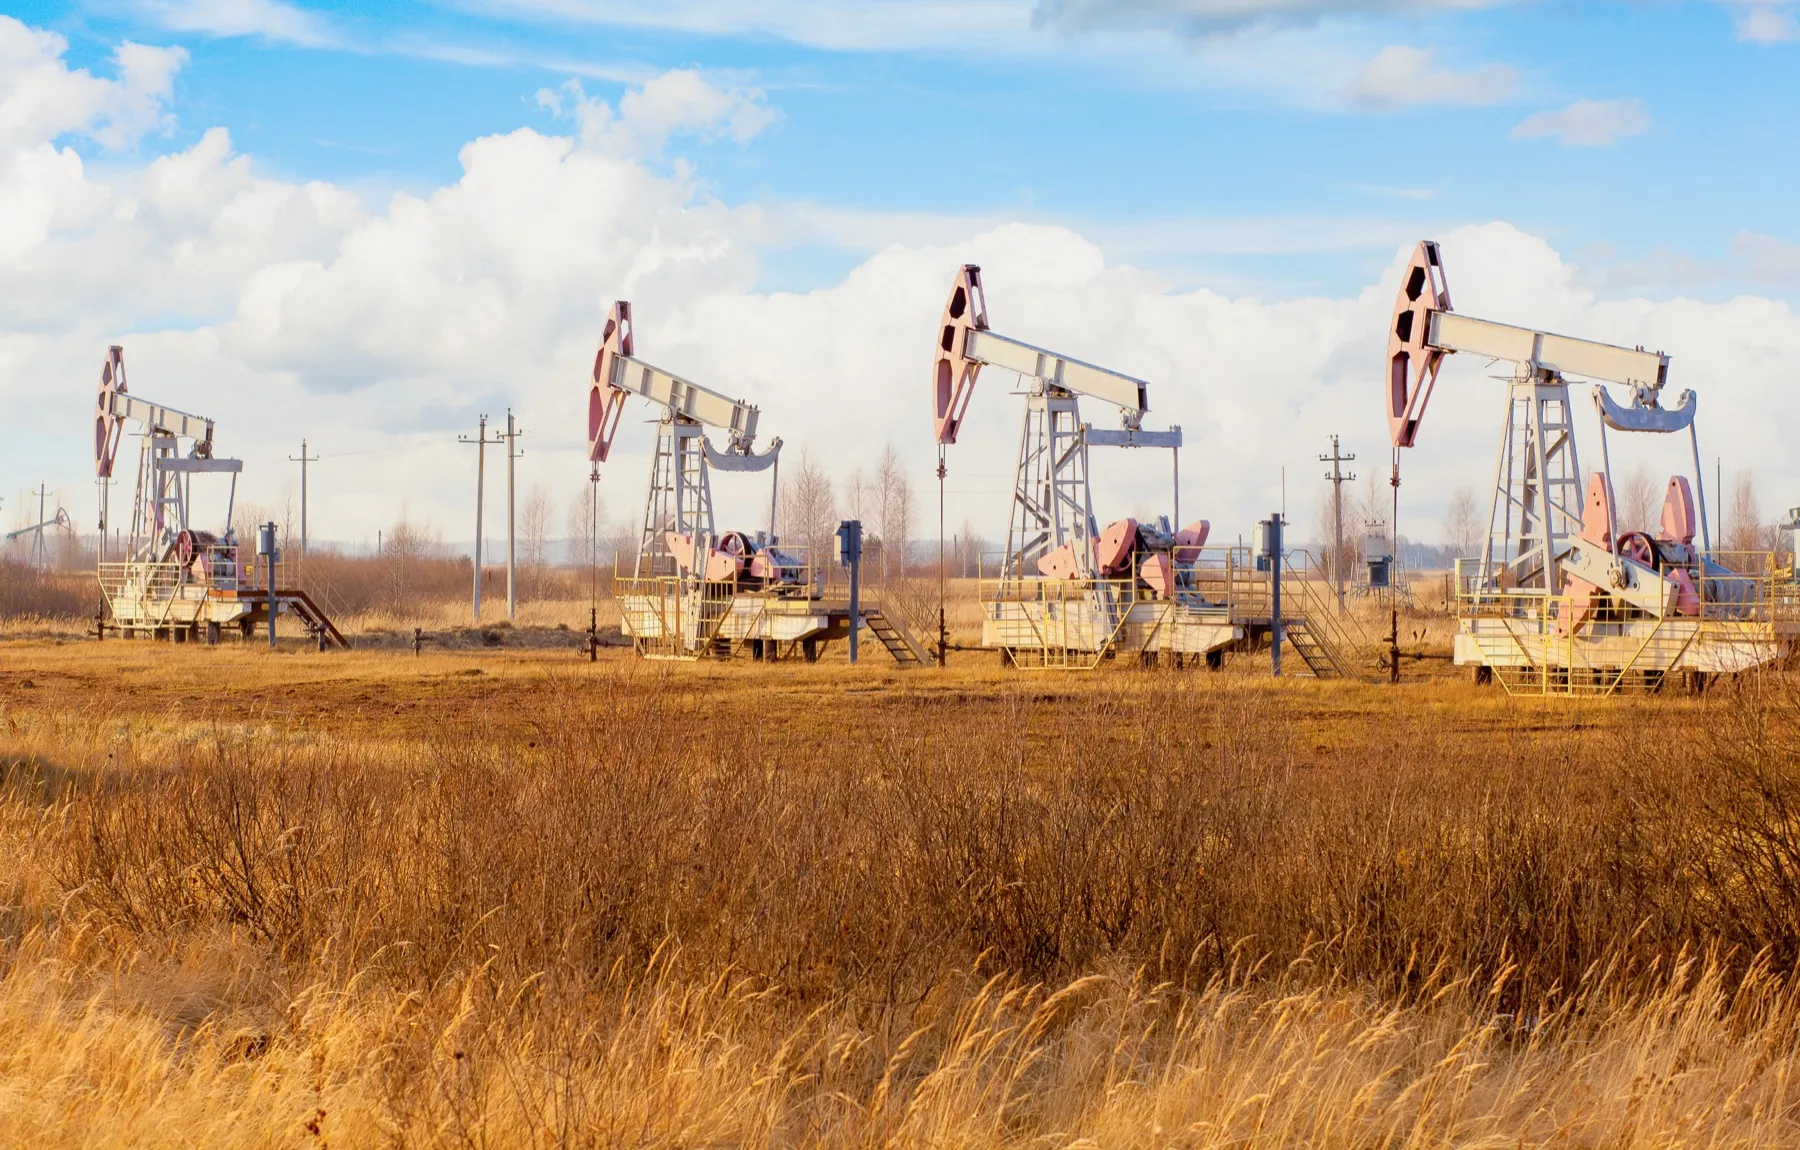
Four currencies are usually put in this group:
- The Canadian dollar (CAD), linked to crude oil. Energy is Canada’s largest export, and the great majority of its crude goes to the United States.
- The Australian dollar (AUD), linked to iron ore and coal, with gold and natural gas behind them. Most of Australia’s iron ore is shipped to China.
- The New Zealand dollar (NZD), linked to dairy and other farm exports. China is New Zealand’s largest export market.
- The Norwegian krone (NOK), linked to oil and gas from the North Sea, sold mainly to Europe.
The Australian and Canadian dollars are among the most traded currencies in the world; the New Zealand dollar and the krone are smaller markets. Most retail traders meet the group through AUD/USD, USD/CAD and NZD/USD. The krone is usually traded through EUR/NOK or USD/NOK, often with wider spreads than the majors.
The second column in each card is the main buyer. The customer’s health matters as much as the commodity price. The Australian dollar responds to Chinese steel demand as much as to the iron ore price itself, and the Canadian dollar is tied to the US economy in a dozen ways beyond oil. Our guides to AUD/USD and USD/CAD go into each pair in depth; this article explains the mechanism they share.
The opposite of a commodity exporter is a commodity importer. Japan imports nearly all of its energy, so a sharp rise in oil prices raises its import bill and tends to weigh on the yen. Keep that mirror image in mind: when oil moves, it rarely moves just one currency.
How commodity prices move a currency: terms of trade
The link runs through a simple idea called the terms of trade: the price of what a country sells abroad divided by the price of what it buys. If Canada’s export prices rise 20% while its import prices stay flat, each barrel it ships pays for 20% more imports. The country is richer, even though it produced nothing extra. Central banks track this closely; the Reserve Bank of Australia, for example, publishes an index of commodity prices and comments on the terms of trade in its policy statements (RBA).
Better terms of trade reach the currency through two routes, one fast and one slow.
The fast route is the market itself. Traders and funds know the relationship, so when oil rises they buy Canadian dollars in anticipation, often within minutes. This is why CAD can strengthen on an oil move before any Canadian data confirms that anything has changed.
The slow route is the real economy. Exporters earn more US dollars and convert part of them into their home currency to pay wages, taxes and suppliers. Higher profits attract investment into mining and energy. Government revenue rises. Growth and employment pick up, inflation may follow, and the central bank becomes less likely to cut interest rates and more likely to raise them. That last step matters most, because interest-rate expectations are the strongest single driver of major currencies, as our guide to how interest rates affect currency explains.
Commodities are only one of the five forces that move a currency. The map below places them alongside the others for the Canadian dollar. Tap each driver to see which way it pushes, and notice that rates, growth and commodities often point the same way for CAD, which is why oil can look so powerful in good times.
▲ Higher rates
▼ Lower rates
Higher interest rates attract foreign money seeking better returns, which must be converted into the currency first. Rate expectations are the single biggest driver of major currencies.
The five main drivers of the Canadian dollar. For CAD, trade and commodities usually means oil, and it often lines up with growth and interest-rate expectations rather than acting alone.
The Academy lesson on what moves currencies covers all five drivers, and the lesson on commodities and currency correlations is the hub for this article.
The four commodity currencies, one by one
Each commodity currency has its own commodity, its own customer and its own quirks. Knowing the quirks is what stops you from expecting a textbook link that is not there.
CAD and oil
The Canadian dollar is the textbook example. Canada holds some of the largest oil reserves in the world, much of it in the oil sands of Alberta, and nearly all of its crude exports cross the border into the United States. When oil rises, Canada’s income rises, and USD/CAD (which is quoted as Canadian dollars per US dollar) tends to fall. When oil falls, USD/CAD tends to rise. The most striking recent example was the oil collapse of 2014 to 2016, when crude prices more than halved and the Canadian dollar weakened sharply against the US dollar.
Two features soften the link. First, Canada’s economy is closely tied to the US, so US growth, US interest rates and trade policy between the two countries can matter as much as the oil price. Second, Canadian crude often sells at a discount to the US benchmark because of pipeline and refining constraints, so the headline oil price is not exactly what Canada earns. The Bank of Canada publishes its own commodity price index and regularly discusses oil in its rate decisions (Bank of Canada).
AUD, iron ore and China
Australia is the world’s largest exporter of iron ore, which goes into steel, and a major exporter of coal, natural gas and gold. Most of the iron ore goes to China, so the Australian dollar acts as a proxy for Chinese industrial demand. Chinese data such as industrial production, property investment and credit growth can move AUD/USD more than some Australian releases. Because AUD is also a liquid, higher-beta currency, it is widely used as a way to express a view on global growth, which makes it one of the most risk-sensitive major currencies.
NZD and dairy
New Zealand’s largest goods export is dairy, mainly milk powder, butter and cheese, much of it sold to China and Southeast Asia. Dairy prices are set at regular online auctions held twice a month, and a large surprise at one of them can nudge NZD/USD. In practice the New Zealand dollar follows the Australian dollar closely, because the two economies share customers and both respond to Chinese demand and risk mood. Our NZD/USD guide covers the pair in detail.
NOK and North Sea oil
Norway is a large oil and gas producer, and the krone does tend to rise with energy prices. But Norway channels much of its petroleum income into a very large sovereign wealth fund that invests abroad, rather than letting all of it flow straight into the domestic economy. That deliberate buffer, together with the krone’s smaller market, makes NOK a less reliable oil proxy than its exports alone would suggest. In a global panic the krone can be sold hard simply because it is a small currency, whatever oil is doing.
Why the commodity link weakens or breaks
The commodity link is loose, and it is weakest when traders lean on it hardest. The lesson on correlations puts it in one line: correlations weaken when one currency has its own story. Here are the stories that most often get in the way.
Interest rates override commodities
If the Bank of Canada is cutting rates because domestic growth is weak, CAD can fall while oil rises. The rate story is usually stronger, because it changes what investors earn on every Canadian dollar they hold. The same is true of the Reserve Bank of Australia and AUD. Before you read anything into a commodity move, check what the market expects from the central bank. The Academy lesson on central banks shows how to read that.
Why the price rose matters
Oil can rise for two very different reasons, and they do not affect currencies in the same way.
When oil rises because the world economy is booming, the rally comes with rising share prices, firm metals and confident investors: every force points the same way and commodity currencies rise cleanly. When oil rises because supply has been cut or disrupted, higher fuel costs act like a tax on growth. Canada still earns more per barrel, but the nervous mood that often comes with a supply shock can weigh on all risk-sensitive currencies, and the Australian dollar in particular may fall.
Risk mood can swamp everything
AUD, NZD and CAD are also risk-sensitive currencies. In a sharp sell-off, investors dump them and buy the safe havens, often regardless of what commodity prices are doing. Switch the mood below to see which currencies tend to rise and fall together.
Tap a currency to see why it behaves this way.
Risk-on and risk-off tendencies. The commodity currencies sit on the risk-on side, so a panic can push them lower even while their commodity holds up. Tendencies, not rules.
Our guide to risk-on and risk-off explains this mood in full. For a commodity currency trader a risk-on/risk-off shift usually moves the commodity and the currency together, which can make the commodity link look stronger than it is.
Already priced in, and the US dollar effect
Markets trade on expectations. If an oil rally was widely expected, the currency may have moved weeks before, and the actual rise changes little: it is priced in. There is also a dollar effect hiding in the numbers. Most commodities are priced in US dollars, so a broadly weaker dollar tends to lift commodity prices and commodity currencies at the same time. Some of what looks like an oil–CAD link is really both reacting to the dollar.
Why it matters for your positions
These shared drivers create correlations between pairs that have no currency in common on paper. Long AUD/USD and short USD/CAD are both bets on commodity currencies against the dollar. Explore the grid below and tick a basket of positions to count your real exposure.
Typical correlation between pairs
| EUR/USD | GBP/USD | AUD/USD | USD/JPY | USD/CHF | USD/CAD | |
|---|---|---|---|---|---|---|
| EUR/USD | ||||||
| GBP/USD | ||||||
| AUD/USD | ||||||
| USD/JPY | ||||||
| USD/CHF | ||||||
| USD/CAD |
Tap any cell to see what that correlation means for two open positions.
How many times are you really betting on the dollar?
Illustrative long-run correlations between six major pairs, not live data. AUD/USD and USD/CAD sit in opposite blocks, so buying one and selling the other is close to one bet on commodity currencies.
Our guide to currency correlation shows how to measure the link, and the lesson on correlation risk shows how to cap the combined risk.
How to watch commodity prices as context, not signals
The useful way to think about commodity currencies is as background. A commodity price is rarely a reason to enter a trade on its own. It is a reason to trust a setup a little more, to trust it a little less, or to stand aside before an event you cannot control.
A short routine is enough. Before you trade a commodity currency, glance at the commodity that drives it and at its main customer:
| Currency | Commodity to check | Customer to check | Regular events worth knowing |
|---|---|---|---|
| CAD | Crude oil (US and Brent benchmarks) | US growth and trade news | Weekly US oil inventory report; OPEC+ meetings; Bank of Canada decisions |
| AUD | Iron ore, coal, copper as a growth gauge | Chinese industrial and property data | Chinese monthly data; RBA decisions |
| NZD | Dairy prices | China and the AUD | Dairy auctions twice a month; RBNZ decisions |
| NOK | Brent crude and European gas | European demand | Norges Bank decisions |
In the United States, the Energy Information Administration publishes weekly figures on crude stocks and production, usually on Wednesdays (EIA). The release often moves oil, and through oil the Canadian dollar. Meetings of OPEC and its allies, known as OPEC+, can change output targets and occasionally announce surprises over a weekend. Put both on your economic calendar alongside the usual data; the Academy lesson on the economic calendar shows how to read one.
Then use what you see in one of three ways.
When the commodity agrees with your idea (for example, a bearish USD/CAD setup while oil is firm and rising), you have one more piece of evidence behind the trade. Keep your normal risk; the agreement only adds a little confidence that the setup is not fighting the tide.
When the commodity disagrees (a bearish USD/CAD setup while oil is sliding), ask what your setup knows that the oil market does not. Sometimes there is a good answer, such as a hawkish central bank. Often there is not, and a smaller position or no trade is the honest response.
When a big commodity event is due, such as an OPEC+ meeting over the weekend, the price can gap straight past your stop. Reducing size or waiting until the event has passed is a risk decision, not a forecast.
An oil shock and USD/CAD: a worked example
The chart below is an illustrative sketch of how an oil shock can hit a USD/CAD position. Step through it, then read the numbers in the worked example underneath.
Illustrative USD/CAD sketch, not real data: a long position opened at 1.3600 with a stop at 1.3540, then a weekend oil shock that opens the market at 1.3490, straight through the stop.
Nothing in Canada changed over that weekend. The Canadian dollar moved because its main export did. A commodity-currency pair can be hit by an event in a market you were not watching. A stop loss limits most losses, but it cannot stop a price that never trades at your level; that difference is called slippage. The lesson on stop-loss placement and our guide to position sizing cover the arithmetic behind steps 2 and 3.
Common mistakes with commodity currencies
Trading the commodity chart instead of the currency
Seeing oil rise and immediately selling USD/CAD treats a loose tendency as a trigger. By the time you notice the move, the fast route has usually already moved the currency. Use the commodity as context for a setup on the pair itself, not as the setup.
Assuming the link is constant
The correlation between a commodity and its currency drifts. It can be strong for a year and then vanish for months while a rate story or a political story takes over. Check the recent behaviour of both charts side by side before you rely on the relationship.
Ignoring the customer
AUD traders who watch iron ore but not Chinese data, or CAD traders who watch oil but not the US economy, are missing half the picture. The customer’s health often explains why a currency ignores its commodity.
Stacking commodity trades
Long AUD/USD, long NZD/USD and short USD/CAD can feel like three independent ideas. In a global sell-off they behave like one large position. Count them as one idea and cap the combined risk.
Holding through commodity events at full size
OPEC+ meetings, surprise output decisions and major Chinese data can move commodity currencies when you are away. If you hold over a weekend with a known event, reduce size or accept that your stop may not fill where you placed it.
Frequently asked questions
What are commodity currencies?
Commodity currencies belong to countries whose exports are dominated by raw materials, so their value tends to follow those prices. The main examples are the Canadian dollar (oil), the Australian dollar (iron ore, coal and gold), the New Zealand dollar (dairy) and the Norwegian krone (oil and gas).
Why does the Canadian dollar follow oil prices?
Oil is Canada's largest export, and most of it is sold to the United States. When oil rises, Canada earns more, its terms of trade improve and growth tends to strengthen, which can lead the Bank of Canada to hold or raise rates. Traders know this, so CAD often moves with oil within minutes.
Does the Australian dollar follow iron ore or gold?
Both, to a degree, but iron ore and Chinese demand usually matter more than gold, because iron ore is a far bigger export. AUD also behaves as a risk-sensitive currency, so global share markets and Chinese growth data can outweigh any single commodity on a given day.
Why do higher oil prices weaken the Japanese yen?
Japan imports nearly all of its energy. When oil rises, its import bill grows and its terms of trade worsen, which tends to weigh on the yen. The yen's role as a safe haven can still lift it in a crisis, so the effect is a tendency, not a rule.
Are commodity currency correlations reliable for trading?
They are useful as context but unreliable as signals. Interest-rate expectations, risk mood, the reason a commodity moved and the US dollar itself can all break the link for months. Use a commodity to weigh a setup on the currency pair, and size related trades as one idea.
Free course
Learn this step by step
“Fundamental Analysis” is a free BrokerCut Academy course: 9 short lessons (about 70 minutes), quizzes, interactive tools and a certificate when you finish.
Enrol free